Last Updated: October 27, 2026
Quick Summary
Emergency tree removal insurance requirements center on verifying the contractor's coverage before any crew arrives. Ask for a certificate of insurance showing active general liability with completed operations, workers' compensation, and commercial auto coverage, then call the insurer to confirm the policy is in force. Your tree removal insurance claim also depends on documenting the damage with photos before anything is moved.
- Get the certificate of insurance by email, never accept a verbal confirmation.
- Call the insurer directly to verify the policy is active and in force.
- Photograph all damage before removal begins and throughout the entire job.
- Ask your adjuster how debris hauling is handled before assuming it is covered.
- Never authorize work on a neighbor's tree without confirming ownership first.
Emergency Tree Removal Insurance Requirements: What Homeowners Must Know
A storm drops a pine across your roof at 2 a.m. When that happens, knowing who to call for emergency tree services and what the process involves can help you act quickly. Before you call anyone, you need to understand emergency tree removal insurance requirements, because the decisions you make in the next few hours affect who pays for what.
What a Tree Service Certificate of Insurance Should Show You
Any legitimate tree removal contractor will send this without hesitation. If a company stalls, makes excuses, or says the paperwork is "in the truck," treat that as your answer.
General Liability and Completed Operations Coverage
Look for a policy that names both. A general liability policy without completed operations leaves a gap exactly where tree work creates the most risk.
Workers' Compensation and Commercial Auto Coverage
Commercial auto insurance covers the trucks and chippers parked in your driveway. Ask whether the policy is active and whether equipment is covered in transit. These three coverages, general liability, workers' comp, and commercial auto, form the core of a professional tree service company's insurance package.
Here are the core coverages a legitimate tree service should be able to document before any crew arrives.
| Coverage | What it protects | Note |
|---|---|---|
| General liability | Core of a professional insurance package | Pair with completed operations coverage |
| Completed operations | Closes gap where tree work creates most risk | Needed alongside general liability |
| Workers' compensation | Covers crew members | Confirm it is active |
| Commercial auto | Covers trucks and chippers in your driveway | Ask if equipment is covered in transit |
How Homeowners Insurance Tree Removal Coverage Works
One honest caveat: insurers generally expect you to prevent further damage, not to renovate your yard. Removing a tree that is blocking your driveway or resting on your roof is mitigation. Replanting or reshaping the landscape is not.
When a Tree Hits Your House or a Neighbor's Property
If you are weighing costs against coverage, our breakdown of emergency tree removal costs helps you see what the work involves before you decide how to proceed.
The Emergency Tree Removal Contractor Checklist
- Confirm the company has an active general liability policy
- Confirm workers' compensation coverage for crew members
- Confirm commercial auto coverage for trucks and equipment
- Get the certificate of insurance by email, not verbally
- Call the insurer to verify the policy is in force
- Ask for a written scope of work and a written estimate
- Confirm the company will provide photos before and after
- Ask who handles permits if street or right-of-way access is needed
- Get a direct contact number for the crew lead
- Never pay the full amount upfront
Who Authorizes Work and How Insurer Approval Fits In
Never authorize removal work on a neighbor's property or a shared boundary line without confirming who owns the tree and who is filing the claim. Paying for work you had no authority to order is a common and expensive mistake.
Filing a Fallen Tree Insurance Claim: Documentation That Matters
A fallen tree insurance claim rises or falls on documentation. Start taking photos before anything is moved, and keep taking them through the entire job. The goal is a file an adjuster can read in five minutes and approve without a second visit.
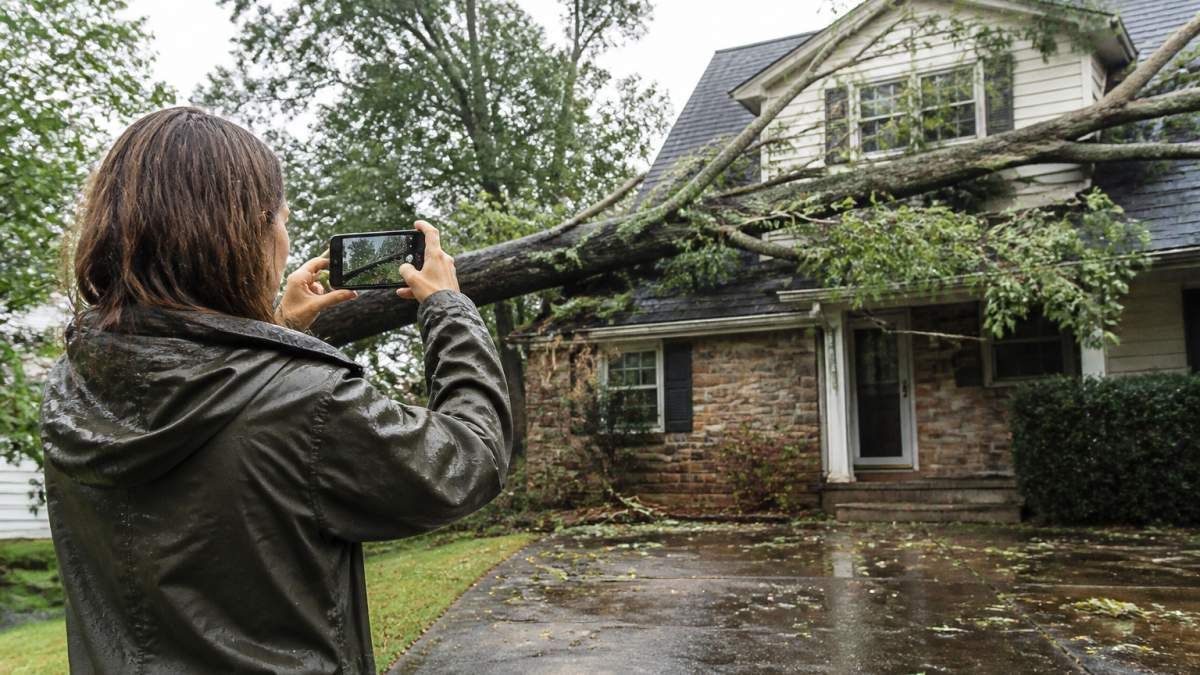
Build the Claim File in This Order
Keep the entire file in one folder, digital or paper, and name files by date. When the adjuster asks for something, you want to send it in one message, not five.
What Adjusters Typically Ask For
Be careful with debris hauling. Urgent removal costs, debris hauling, and preventive removal may be treated differently under your policy, and the debris line item is often where homeowners are surprised. Ask your adjuster specifically how debris removal is handled before you assume it is covered.
Renters, Landlords, and Shared-Property Responsibilities
Landlords should confirm their policy covers removal and debris hauling, and should document tree health before storm season. On shared property, such as a boundary tree between two homes, confirm ownership first and put any cost-sharing agreement in writing before work begins. If the tree was dead or visibly hazardous and you had been warned, that history matters, which is why documented tree health is worth keeping year to year.
Contractor Verification and Liability Checks Before the Crew Arrives
If you have already chosen removal, review our tree removal services.
Request an Emergency Tree Service Estimate From Arbortech of Anderson
Arbortech of Anderson is a locally owned, family-operated tree service that has served the Upstate since 2008, providing emergency tree services, hazardous tree removal, storm damage cleanup, trimming, and pruning with experienced crews and modern equipment.
Our team works with professionalism and accountability.
Get started with Arbortech of Anderson and get a clear estimate for the work your property needs. Reach out through our contact page to request yours.
Frequently Asked Questions
What insurance should an emergency tree removal company have?
Ask for a current certificate of insurance showing general liability, workers' compensation, and commercial auto coverage. General liability should include completed operations so damage that surfaces after the crew leaves is still covered. Workers' compensation matters because an injured crew member could otherwise pursue the homeowner. Commercial auto covers the trucks and equipment on your property. Verify the policy is active by calling the insurer listed on the certificate, and confirm policy limits are high enough for the size of the job.
Does homeowners insurance cover emergency tree removal?
Homeowners insurance tree removal coverage usually applies when a tree hits a covered structure, blocks a driveway or access route, or poses an imminent threat to the home. Many policies cap removal payouts, often at a few hundred to a few thousand dollars per tree, so check your policy limits before assuming full reimbursement. If the tree simply falls in the yard without damaging anything, coverage is often limited or absent. Read your declarations page and call your agent before authorizing non-emergency work.
Should I request a certificate of insurance from a tree service?
Yes. A tree service certificate of insurance confirms the contractor carries general liability and workers' compensation coverage. Request it before work begins, check the named insured matches the company you hired, and confirm the policy expiration date has not passed. If the certificate lists additional insured status, ask whether your property can be added. This step protects you from liability if a crew member is injured or the crew damages your home, fence, or a neighbor's property during emergency tree removal.
What should I document after storm damage to a tree?
Photograph the tree and any damaged property from multiple angles before cleanup begins, and date the images. Keep a written timeline of the storm, the damage, and every call to your insurer or contractor. Save receipts for emergency mitigation such as tarping or temporary repairs. Do not discard damaged limbs or debris until the adjuster has seen them. If a contractor removes the tree, get a written invoice that itemizes labor and disposal so your fallen tree insurance claim has a clear paper trail.
Storm damage rarely waits for business hours, and the paperwork should not slow you down. Call Arbortech of Anderson for an estimate and let an experienced local crew handle the removal while you focus on your claim.